 Rimani

Condizioni di trading
Strumenti


The final GDP estimate for the UK in Q2 was revised sharply higher from the preliminary reading — quarterly growth was revised up to 0.5% and year-on-year to 1.4%. Positivity is weaker in Q3: the composite PMI fell from 52.5 to 51.7, a three-month low; the services PMI fell from 52.5 to 51.7; new orders contracted for the first time in three months; and export sales are falling even faster.
At the same time, inflation rose to 3.1% in August, and the Bank of England's own projection shows headline inflation potentially above 4% in early next year. That acceleration is almost entirely energy-driven: Brent is holding near $100, and UK wholesale gas prices in early September exceeded 188 pence/therm — the highest since late 2022 and more than double year-to-date.
This combination — an external shock with domestic weakness — puts the BoE in an awkward position. At the Nomura conference in London, Catherine Mann was clear: the BoE "will have to raise rates at some point" — not just to react to current inflation prints but to "protect its reputation," i.e., to avoid an unanchoring of inflation expectations due to perceived regulatory indecision.
Traders fully price in at least one hike by year-end and put the chance of a second at roughly 50%. The problem is PMI signals growth approaching zero — S&P Global estimates quarterly GDP growth at only 0.1%. That raises the specter of stagflation: rate hikes will squeeze already weak demand, while avoiding hikes risks entrenching inflation near 4%.
Demand is indeed falling noticeably. The British Retail Consortium recorded a drop in consumer expectations for the economy over the next three months from –28 in August to –34 in September, and expectations for personal finances fell from –9 to –15. BDO's high-street sales tracker is even starker: in September total discretionary retail sales fell 0.3% y/y — the weakest September since 2019 excluding pandemic years — and online sales fell 1.1%, the worst reading on record. CBI data show retailers cutting orders at the fastest pace since the series began in 1983.
Net short positioning in GBP rose over the reporting week to -£7.62bn; the implied fair price is moving lower, with no signs of a turn yet.
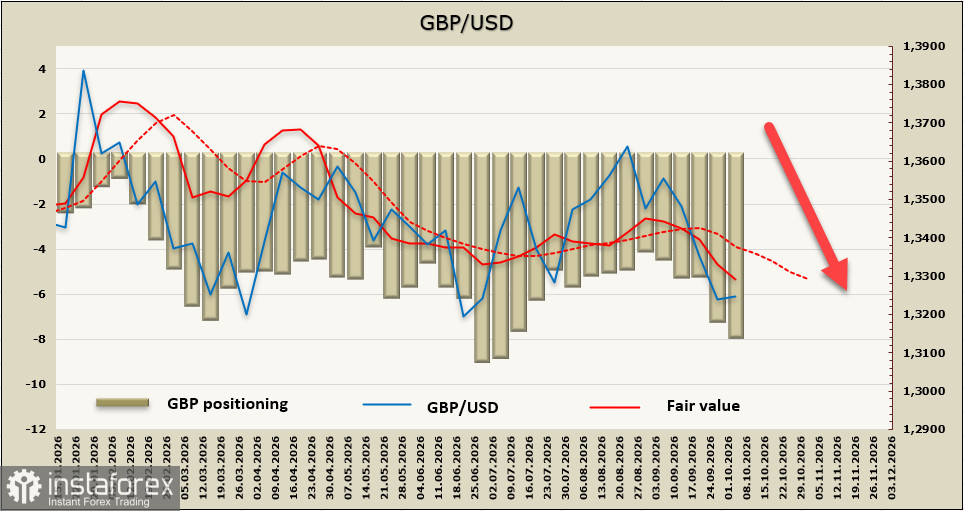
A week ago we expected a decline toward 1.3139 — that target remains valid. After the sharp drop, the pound is consolidating, and we expect the decline to resume after consolidation ends. Resistance sits at 1.3295–1.3310, the top of the consolidation range; the probability of a sustained move above that zone is low.
Le recensioni analitiche di InstaForex ti renderanno pienamente consapevole delle tendenze del mercato! Essendo un cliente InstaForex, ti viene fornito un gran numero di servizi gratuiti per il trading efficiente.


