 Rimani


Condizioni di trading
Strumenti


After yesterday's session, the euro and the British pound again fell sharply against the US dollar. The rebound seen earlier proved short-lived and was replaced by a fresh wave of demand for the US currency. The trigger was another escalation in the Middle East conflict and the release of the minutes from the September Fed meeting, while the European data published against that backdrop went largely unnoticed.
Oil reversed higher again and posted a fairly strong rally, and 10-year US Treasury yields followed suit. Bonds are being sold, demand for US government debt is falling — which is bad for the US economy but good for the dollar, whose demand, as we can see, has noticeably returned. By way of comparison, on October 5, the 10-year yield stood at 5.26%, and Brent traded near $101, so the recent oil reversal is adding pressure on energy-importing currencies, with the euro among the first to suffer. Ten-year yields are now trading above 5.31%.
The released German and French data were decent, but they did not help the euro. German industrial production jumped 2.0% in August vs. a 0.5% forecast after a 1.2% decline in July, and France's trade balance was also acceptable. The gain for German industry and exporters is obvious, but the market ignored these figures because attention was focused elsewhere. What tipped the scales? The Fed minutes — more on that below.
The minutes of the September meeting, at which the policy rate was raised to a 3.75–4.00% range, showed that all 19 participants supported the decision. The vote was unanimous, unlike the July meeting where it was 9–3. Most committee members believe another hike will be needed before year-end, and a number of participants think the rate still does not sufficiently restrain inflation, so more aggressive action remains possible. Inflation risks are biased to the upside. Notably, the Fed separately discussed how to prepare tools for stress in the bond market — which is happening now — but no specifics were provided. Another interesting detail is that artificial intelligence was named a factor capable of adding to inflation. That topic is being discussed globally, and price growth is no longer driven only by energy.
In my view, supporters of a strong dollar are the winners here, while those who expected a pause until 2027 are the losers. I believe a December hike is already priced in, while an October move still looks unlikely and remains a pause scenario — especially given the US mid-term elections on November 3. It is unlikely the new Fed chair Kevin Warsh would move against President Trump and push rates substantially higher now; there is no obvious need, and that aligns with the minutes' conclusions. Recall that in September Logan allowed for at least another 50 basis points, so disagreements about the depth of the cycle remain — they simply do not prevent unanimity on the next step.
Let's look at the economic calendar. In the first half of the day, Germany's trade balance is due, and it is unlikely to have a major impact on the euro. Attention will likely shift to the Eurogroup meeting and to the ECB's post-policy-meeting report. Remember, the ECB also raised its rate to a 2.50% deposit rate in September, and it will be interesting to see how policymakers view further tightening. If the report is more hawkish than markets expect, that could produce an upward correction in the euro during the first half of the day.
In the UK, a lending conditions report is due, and speeches by Megan Greene and Bank of England Governor Andrew Bailey are scheduled. The British economy sits between two fires — high inflation on one side and slowing growth and labor market problems on the other — so there is no rush on rates. Greene was among the three committee members who in July voted for immediate tightening, so her remarks will draw extra attention and any new hints could move the pound. From US releases, we will see weekly initial jobless claims — the forecast is around 200k, a normal figure, nothing new. I also expect wholesale inventories, where a 0.7% rise for August is pencilled in, matching July.
EUR/USD
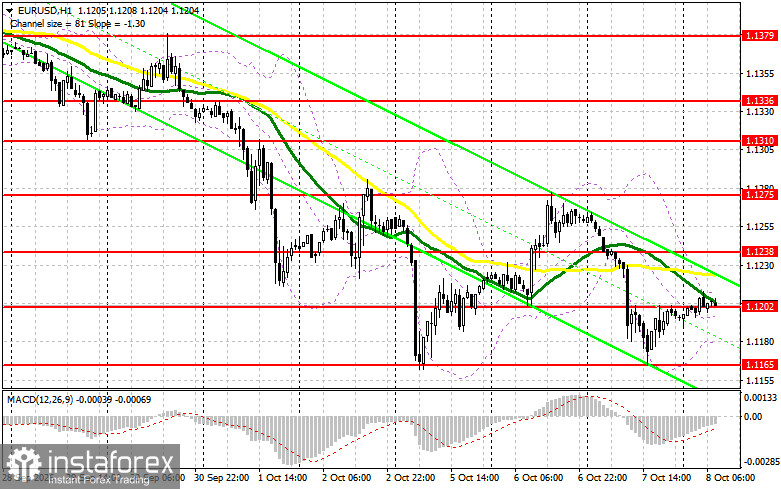
There is a good level at 1.1202 to enter long positions. A false break there would give a chance for a return and correction to 1.1238; a close above would open the way to 1.1275, with a further target at 1.1310, where I will look to sell into strength on a 25–30 pip pullback. Short positions from 1.1238 are considered on a false breakout, as are shorts from 1.1275. If bulls fail to show at 1.1202, a return and close below that level would be a reason to add shorts targeting the break of 1.1165, which was tested on October 5 and again yesterday. A break and close below would open the path to 1.1133 and then to 1.1097, where I would buy the rebound for 25–30 pips. Longs from 1.1133 or 1.1165 are only possible on a failed breakout.
GBP/USD
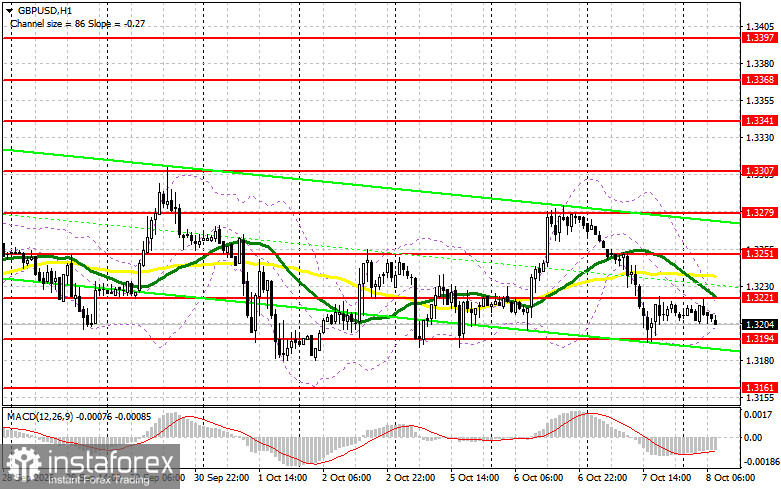
The story is similar. Consider buying around 1.3194 on a false breakout, aiming for a return to 1.3221. If buyers do not appear at 1.3194, the pound sterling will likely revisit monthly lows, and I would expect more aggressive buying near 1.3161 (long positions on a false breakout) or buy a rebound from 1.3128 targeting 25–30 pips. Sells could be opened from 1.3221 — the upper band of the sideways channel we've traded since September 25 — but only on a false breakout. A failed hold at 1.3251 would also justify shorts, while I will look to sell into strength at 1.3279 for a 25-pip move.
I lean toward the view that as long as oil is rising, US bond yields are climbing and the Federal Reserve shows unity on monetary tightening, the dollar retains the advantage. I would venture that the euro will get relief only if the ECB's report proves hawkish, and the pound will remain hostage to remarks by Greene and Bailey. It's possible that until the elections on November 3, the currency pairs will react mainly to oil and yields rather than to regional data.
Le recensioni analitiche di InstaForex ti renderanno pienamente consapevole delle tendenze del mercato! Essendo un cliente InstaForex, ti viene fornito un gran numero di servizi gratuiti per il trading efficiente.


