 Anuluj

Warunki handlowe
Narzędzia


The September producer-price release — up 6.8% year-on-year — may seem to signal a slowdown in inflationary pressure along production chains (consensus was 7.6%). However, import prices in yen soared 24.5% year-on-year, while costs for chemicals, plastics and non-ferrous metals rose 13.3%, 12.8% and 40.2% respectively. That means yen weakness, combined with persistent geopolitical tension in the Middle East, continues to transmit external cost pressures into the Japanese economy with growing force; the moderation in headline PPI only masks this structural process. Economists surveyed by Reuters explicitly noted that producer prices "support the Bank of Japan's intention to raise rates in due course," despite no urgency for an immediate hike.
Japanese crude-oil imports in June rose to 8.6 million tonnes, exceeding last year's level for the first time in four months. Shipments from the United States drove the recovery, doubling from May to 2.7 million tonnes—almost one-third of total imports. Japan's dependence on the Middle East fell from 94% in 2025 to 62.3% by June.
US crude, however, costs Japan roughly 15% more — a gap driven by higher shale-oil production costs and logistics. Moreover, Japanese refineries have historically been optimized for the heavier Middle Eastern crudes; switching to lighter US grades requires additional capital expenditure to reconfigure processes. From a supply-availability standpoint, there is no immediate threat of disruptions. But if the Strait of Hormuz remains effectively closed for a prolonged period and oil prices stay at current levels, Japan would face a compounding set of shocks.
Higher energy import costs worsen the terms of trade and directly reduce real national income. If oil stays above $100/bbl and import prices in yen keep rising, the current-account deficit could widen to levels not seen since the first oil shock — putting fundamental downward pressure on the yen as financing the deficit requires steady inflows of foreign capital.
A second channel is through real household incomes. Rising energy and food prices have already contributed to stagnation in private consumption. If high prices persist, real incomes will keep shrinking, further depressing consumption and GDP growth.
A third channel is via corporate investment. Uncertainty about future energy prices and supply reliability encourages companies to delay capex.
A fourth channel is via inflation expectations. If elevated energy costs persist, the BOJ may be forced to raise rates more aggressively than domestic conditions alone would justify. That could trigger a sharp economic slowdown and weaken the yen as markets price in a recessionary scenario.
The market still expects the BOJ rate to be 1.25% in December as the base case. However, if the energy shock is prolonged, USD/JPY should remain volatile, the policy-rate differential will stay large, and even a December BOJ move would not fully eliminate that gap.
Speculative positioning shows a yen short bias of +$4.93 billion for the reporting week — a sizable overweight — yet the implied price has no clear trend and has reverted to the long-term mean.
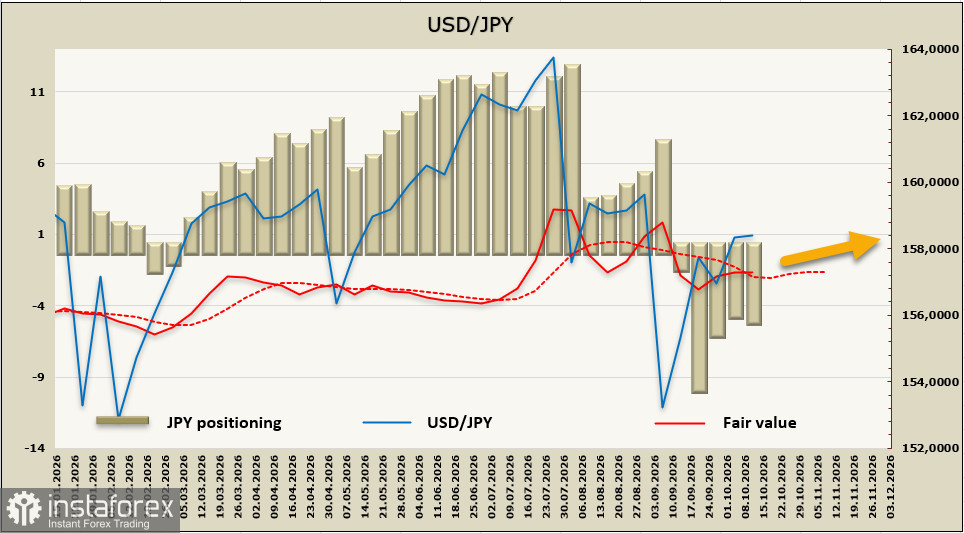
USD/JPY has returned to the middle of the wide range that dominated 2026, and the near-term direction is unclear. In the previous note, we suggested the pair would remain within 157–160 absent a clear driver; little has changed over the past week. Resistance sits at 160.35; while the pair remains below that level, the probability of renewed downside appears higher than a resumption of the uptrend.
Dzięki analizom InstaForex zawsze będziesz na bieżące z trendami rynkowymi! Zarejestruj się w InstaForex i uzyskaj dostęp do jeszcze większej liczby bezpłatnych usług dla zyskownego handlu.


